

Key Takeaways
- Homeownership remains a leading path to building personal wealth, despite elevated interest rates and home prices.
- The market has shifted, giving buyers more leverage in negotiations.
- Evaluating personal circumstances and financial readiness is critical before making a purchase.
- Long-term appreciation and equity growth can outweigh short-term market volatility.
Understanding the Current Housing Market Landscape
The journey toward homeownership has been anything but straightforward in recent years, largely due to significant changes in the housing market. Mortgage rates are now rarely below 6%, and buyers are often faced with record-high prices in many regions of the country. These trends have compelled many potential homeowners to reconsider their plans. However, for those seeking guidance, Boca Grande real estate agent Jamie Curry offers insights that can help prospective buyers make informed decisions.
Many buyers also grapple with competition and a limited supply in certain markets. As mounting affordability challenges dominate headlines, understanding the real costs and benefits of owning a home has never been more crucial.
The Financial Benefits of Homeownership
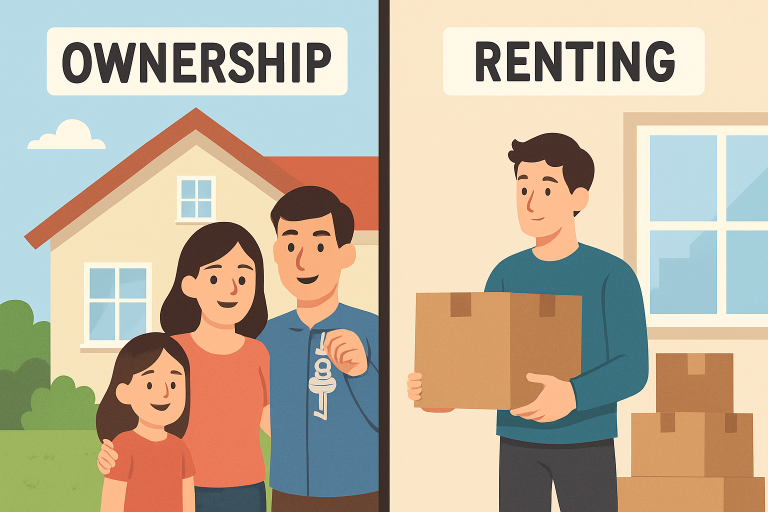
Traditionally, owning a home has been viewed as an essential step toward financial security. Homeownership builds wealth in ways that renting often cannot match. According to a 2024 Aspen Institute Financial Security Program report, homeowners have a median net worth of $400,000, whereas renters have a median net worth of just $10,400. This disparity highlights just how powerful homeownership can be as a wealth-building tool.
As a homeowner pays down the principal on their mortgage, their home increases in value, contributing to greater long-term financial stability. Renters, on the other hand, may see their wealth limited, as they miss out on home appreciation and equity growth.
Leveraging Equity and Appreciation
Equity represents the portion of a property the homeowner truly owns and grows each month with every mortgage payment. Unlike many investment assets, the value of real estate has generally trended upward for decades. The median U.S. home price, for example, reached $410,800 in the second quarter of 2025, according to Zillow Research. Significant appreciation in many markets has yielded impressive returns for homeowners, rewarding those willing to invest in property and remain patient over the years.
Assessing Affordability: The 28% Rule
One of the key ways buyers can responsibly assess their readiness to buy is by adhering to the “28% rule.” This financial guideline advises that all housing-related costs, including mortgage, taxes, and insurance, should not exceed 28% of the household’s gross monthly income. Sticking to this limit can help buyers avoid financial strain, especially in high-cost markets with elevated mortgage rates. Serious buyers should run the numbers carefully and work with reputable agents and financial professionals to determine the affordability of any prospective purchase.
It’s worth noting that in today’s environment, adhering to this rule is often easier said than done. Rising costs have made homeownership more challenging, especially for first-time buyers and in cities where incomes have not kept pace with home prices.
Market Dynamics: A Shift Towards Buyers
Market conditions are beginning to evolve, however. In June 2025, the housing market experienced a notable shift, with nearly 500,000 more home sellers than buyers, resulting in a 33.7% seller surplus. This trend, the largest surplus since tracking began in 2013, means more choices for buyers and greater potential for negotiation on price and terms. Buyers who were previously sidelined by competition or limited inventory may now have a window of opportunity.
Long-Term Investment Perspective
Despite market fluctuations, real estate has a long track record of rewarding patient investors. Over the five-year period from December 2019 to July 2025, home prices nationwide jumped nearly 50%. Buyers with a long-term perspective often benefit from these price gains, as market dips tend to be temporary over decades. For those able to weather short-term volatility, homeownership continues to offer substantial rewards.
Considering Personal Circumstances
Even with positive long-term trends, buyers should not overlook their own unique circumstances. Stable employment, ample savings for a down payment and closing costs, and clear long-term goals are all factors that heavily influence the decision to buy. Before taking the plunge, it is wise to consult a financial advisor and a local real estate agent to ensure that the timing and financial commitment align with your broader life objectives.
Final Thoughts
The current housing market presents both challenges and opportunities for those considering homeownership. While high mortgage rates and rising prices have shifted the affordability equation, the potential to build equity and enjoy long-term appreciation makes buying a home an investment worth careful consideration. Evaluating your financial readiness, market outlook, and personal ambitions will ensure that your decision aligns with both current realities and future goals.
