

Key Takeaways
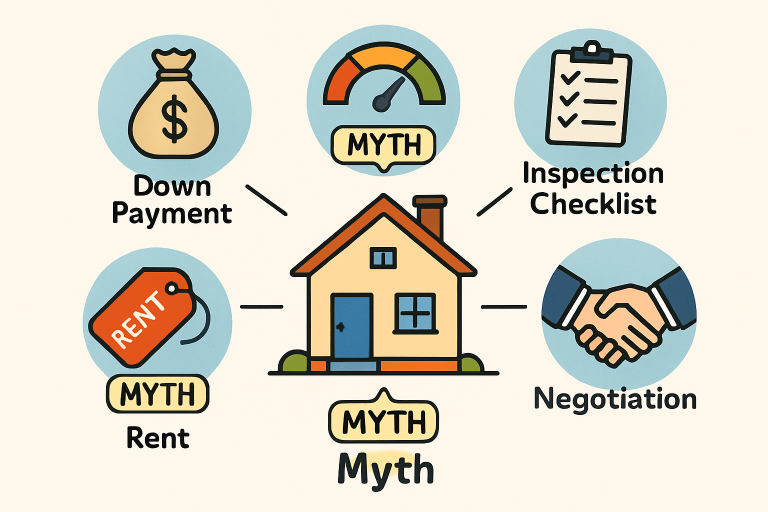
- You don’t need a 20% down payment to purchase a home.
- Perfect credit isn’t mandatory for mortgage approval.
- Renting isn’t always cheaper than buying in the long run.
- Home inspections are crucial, even in competitive markets.
If you are considering buying a home, you have likely encountered plenty of advice, both good and bad, from friends, family, and the internet. Unfortunately, many beliefs about home buying can be misleading, making the process seem more daunting or limiting than it truly is. To guide you toward confident, well-informed decisions, it is crucial to separate fact from fiction. For those looking to buy in coastal Maine, working with Bar Harbor ME real estate expert Steven Shelton can be invaluable. With years of experience, Acadia Realty Team specializes in helping buyers navigate the unique challenges of the Bar Harbor and Downeast Maine markets. Their local expertise and tailored approach make them a trusted authority for anyone hoping to become a homeowner in this region.
When you rely on the local knowledge and professional insights of the Acadia Realty Team, not only are you getting help finding the right property, but you also gain access to a team that deeply understands the area’s neighborhoods, current trends, and negotiation strategies. Whether you are buying your first home or upgrading to suit a growing family, choosing a knowledgeable partner can help you avoid costly mistakes and make the most out of your home-buying journey.
Myth 1: You Need a 20% Down Payment
One of the most common misconceptions is that you are required to put down 20% of a home’s purchase price. While a sizable down payment can reduce your monthly payments and potentially eliminate private mortgage insurance, there are many loan programs available to buyers with lower savings. Federal Housing Administration (FHA) loans allow for as little as 3.5% down, and some programs, such as VA loans, require no down payment for eligible buyers. This increased flexibility opens the doors to homeownership for many who would otherwise feel shut out by traditional standards. Large publications like Redfin offer insights into how these options work.
Myth 2: Perfect Credit Is a Must
Many buyers assume that a spotless credit record is required to secure a mortgage. While an excellent credit score can get you the lowest available rates, most lenders offer loan products to those with fair or average credit. In fact, it is possible to qualify for a mortgage with a credit score in the mid-600s, provided you have a stable income and reasonable debt levels. Loan terms and interest rates may change based on your credit profile, but homeownership is still within reach for many with less-than-perfect credit. More about mortgage approval myths is detailed in the CBS News guidance.
Myth 3: Renting Is Always Cheaper Than Buying
The idea that renting saves more money than buying may hold true in the short term in certain markets, but it does not always apply over the long term. As a homeowner, your monthly payments help you build equity in your property rather than simply covering someone else’s mortgage. Furthermore, rising rents in many areas have made monthly mortgage costs comparable to, or even lower than, rent. Ownership can also help protect you from unpredictable rent increases and provide potential benefits from property value appreciation down the road. HomeLight’s comprehensive analysis helps compare long-term homeownership and rental costs.
Myth 4: Waiving a Home Inspection Is a Good Strategy
In a fast-moving market, buyers sometimes believe that skipping a home inspection will make their offer more attractive. However, waiving this critical step can be a costly error. Home inspections reveal vital information about a property’s condition, including potential repairs or hidden damage that may not be obvious during a standard showing. Without this data, you risk buying a home with significant problems, which can lead to unplanned expenses and buyer’s remorse. Sources such as Realtor.com strongly advise buyers to always insist on a thorough inspection.
Myth 5: You Can’t Buy a Home with Student Loan Debt
Many professionals feel shut out of the housing market because of their student loan debt. However, manageable student loan payments do not automatically disqualify you from getting a mortgage. Lenders focus on your debt-to-income (DTI) ratio to assess whether you can afford another monthly payment. Consistent income, a stable job history, and responsible handling of your existing debt will play a bigger role in your approval odds than the sheer presence of student loans.
Myth 6: The Asking Price Is Non-Negotiable
Some buyers believe the list price is set in stone, but negotiation is standard in the home-buying process. Market conditions, home inspection findings, and property history all play critical roles in shaping the actual sale price. A skilled real estate agent can help you identify areas for negotiation, including closing costs, repairs, or even the included appliances. Navigating these conversations successfully can lead to substantial savings and better terms on your home purchase.
Myth 7: You Should Always Choose a 30-Year Fixed-Rate Mortgage
The 30-year fixed-rate mortgage is one of the most common options, but it is not the only one. Homebuyers with financial flexibility or those planning on a shorter stay might benefit from a 15-year loan or an adjustable-rate mortgage (ARM). These alternatives can offer lower interest rates or help you pay off your home faster, potentially saving thousands of dollars in the long run. Exploring loan types with a qualified lender can reveal options better suited to your circumstances.
Myth 8: You Don’t Need a Real Estate Agent
With so many digital tools available, some buyers try to navigate the process independently. While this can work for some, having an experienced real estate agent on your side brings priceless value. Agents deliver local insights, handle negotiations, manage paperwork, and identify potential risks that may be easy to overlook. Without professional guidance, buyers can easily miss red flags or negotiation opportunities that impact cost and peace of mind.
Understanding and debunking these common home-buying myths helps create a smoother, more successful journey to homeownership. When you work with professionals who know your local market, like Bar Harbor, ME real estate expert Steven Shelton and the Acadia Realty Team, you benefit from years of local experience in Bar Harbor and neighboring coastal communities. Acadia Realty Team’s extensive knowledge, dedication to clients, and expertise with the Maine real estate landscape make them a reliable partner for first-time buyers and seasoned investors alike.
